Mortgage rates have climbed above 7% for the first time since early 2025. For most people, that’s just another headline. For a couple going through a divorce, that one number can make the family home harder to sell and harder to keep.
Below, I explain what this shift means for divorcing couples, the attorneys and mediators who guide them, and anyone considering a buyout right now.
1. Homes can take longer to sell
Existing-home sales fell for the third month in a row in August, and pending sales are moving at their slowest pace since the start of the year. Buyers react quickly to interest rates. As rates go up, fewer people can afford to buy, and homes sit on the market longer.
What that looks like in practice:
More price reductions
Buyers asking sellers to pay for repairs and closing costs
Longer timelines from listing to closing
When a divorce depends on the house selling, those delays affect everything: when the equity gets divided, when each spouse can move on, and how much stress everyone carries in the meantime.
2. Buyouts might be harder to qualify for
When one spouse wants to keep the home, the usual path is a refinance that pays out the other spouse. Today that refinance means stricter lending standards and a much bigger monthly payment.
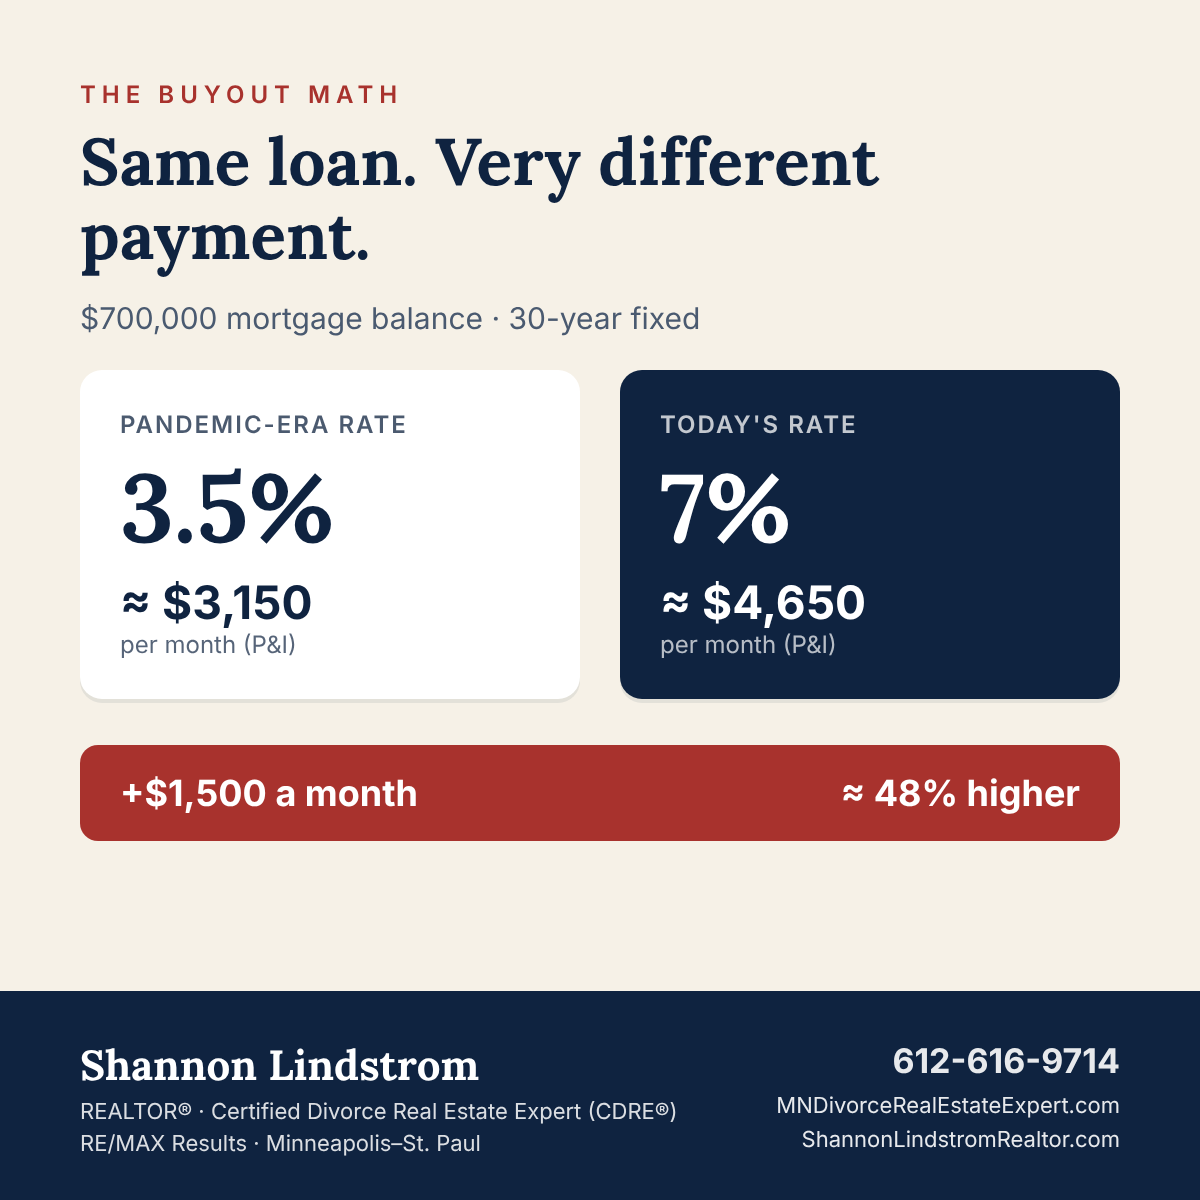
Here’s the math. On a $700,000 balance, going from a 3.5% pandemic-era rate to 7% raises the monthly principal and interest payment from about $3,150 to about $4,650. That’s roughly 48% more on the exact same loan amount.
A jump that size can push the buying-out spouse’s debt-to-income ratio past what underwriters will approve. I expect more buyouts to be denied. Some of those denials will come after a settlement has already been built around the buyout.
3. These rates may be here for a while
NAR Chief Economist Lawrence Yun points to several pressures keeping rates high:
Inflation still running near 3.4%, driven largely by an oil price shock
A growing federal deficit that crowds out private borrowing
“Expect 7% as the new normal,” Yun says. He ties any real relief to lower oil prices, a credible plan to reduce the deficit, or a productivity boost from AI, and he doesn’t expect any of those soon.
What I recommend right now
Nobody wants to hear this, but it’s the market we’re in, and planning for it beats being surprised by it.
If a buyout is being negotiated: Have the spouse keeping the home get a mortgage approval early, before the terms are final. Knowing what they can actually qualify for keeps everyone from building an agreement on a refinance that may never happen.
If the home will be listed: Plan for a longer timeline and possible price adjustments and build that into the settlement and your expectations.
As always, I’m glad to be an extra set of eyes on the real estate side of any case. Here’s hoping for some relief in the months ahead.
Shannon Lindstrom, REALTOR®, CDRE®, MILRES, MRP, VCA
RE/MAX Results | Minneapolis–St. Paul
📞 612-616-9714
🌐 www.MNDivorceRealEstateExpert.com
🌐http://www.ShannonLindstromRealtor.com
🌐 https://www.ilumniinstitute.com/cdre/shannon-lindstrom